Key Takeaways
- An LLC usually continues after an owner dies, but ownership may need to be transferred.
- The operating agreement and estate plan can determine who takes over.
- A deceased owner's membership interest may go through probate.
- Heirs may inherit ownership, receive profits, or sell the interest to other members.
- A succession plan, trust, or buy-sell agreement can help avoid delays and disputes.
Read who can take over after an LLC owner dies, what happens to the ownership interest, when probate may be required, and how to keep the business moving.
When an LLC owner dies, their family, partners, and LLC members find themselves in a difficult spot. On top of grief, there are business-related decisions to make. Without a successor in place, the family and those left behind might face confusion or inheritance disputes.
For anyone facing this issue, the short answer is that in most cases, the LLC doesn’t close when its owner dies. Succession depends on three things: the LLC type, the operating agreement, and the owner's estate planning. This guide covers what happens in a single-member and a multi-member LLC, how probate works, and how to plan ahead.
What Happens When a Single-Member LLC Owner Dies?
If the estate plan or the LLC's operating agreement names a successor or a manager, the heirs have a clear path forward. Even then, they still need to follow the steps in the state's LLC Act.
If a successor is not named in either the estate or operating agreement, the owner's membership interest becomes part of the deceased member’s estate. It then goes through probate, where a court appoints an executor or administrator. Many states refer to this person as the personal representative.
Will an Heir Become a New LLC Member Automatically?
Many states give heirs a window to keep the LLC running. Instead of dissolving the LLC when the sole member dies, these states let someone step in and continue it. In Delaware, for example, the personal representative of the last member can agree in writing to continue the LLC and be admitted as the new member within 90 days. The operating agreement can set a different period. Other states set their own timelines and conditions, so check your state's LLC act.
What Happens When a Multi-Member LLC Owner Dies?
In many cases, the LLC can continue when one owner dies. The surviving members may continue running the business, but the deceased member's rights and the LLC's continued operation depend on the operating agreement and state law. Here are the three most common outcomes:
- Heirs become members. If the operating agreement and state law allow it, heirs may be admitted with the same ownership and vote. In some states, they receive only a share of profits unless the other members approve them.
- Heirs get the profits only. They get a share of the money, but no vote. The other owners keep running the business. Many owners like this setup because they may not want a new partner making decisions.
- The other owners buy the share. The other owners buy the interest. If the operating agreement or a buy-sell agreement requires a buyout, the remaining members or the LLC may purchase the deceased member's interest according to the agreement's terms.
If neither the operating agreement nor the estate plan names an heir, state default LLC law decides.
Can a Multi-Member LLC Keep Operating After Owner’s Death?
Some states have older rules that can close an LLC when a member dies. These rules usually apply only to LLCs formed before a certain date.
- Massachusetts: For LLCs formed before January 1, 1997, a member's death dissolves the LLC unless all remaining members agree to continue within 90 days, or the operating agreement allows it.
- Georgia: For LLCs formed before July 1, 1999, the LLC dissolves 90 days after a member leaves, including by death, unless all other members agree in writing to continue.
Newer LLCs in these states follow different rules. Your operating agreement can also override these defaults. This is why your operating agreement should include a continuation provision. It states that the LLC continues after a member's death and does not dissolve. With that language in place, the surviving members don't have to rely on a state default rule or meet a deadline to keep the business open.
Does an LLC Go Through Probate?
An LLC itself doesn't go through probate. The owner's membership interest usually does. An LLC is a separate legal entity, so it continues to exist when its owner dies. The ownership stake, though, belongs to the owner personally, and that is what the court process deals with.
Probate is the court process that transfers a person's assets after death. It covers assets owned in the person's own name. A membership interest counts as one of those assets, unless it was set up to pass outside of probate.
A court-appointed person takes charge. If the owner left a will, the court usually appoints the executor named in it. If there is no will, the court appoints an administrator. Both are called a personal representative in many states. The court gives this person written authority to act for the estate, and that authority is what allows them to deal with the membership interest.
An LLC interest can skip probate in two common ways:
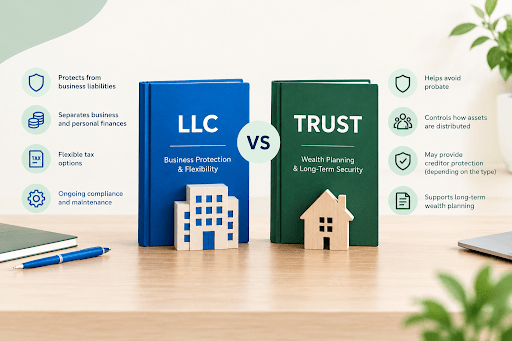
- A trust: The owner transfers the membership interest to a revocable living trust while alive. The trustee then manages it under the trust terms, with no court involved.
- A transfer-on-death provision: Some states may allow transfer-on-death arrangements for LLC interests, and an operating agreement may address transfers at death where state law permits.
What is the LLC Ownership Transfer Process After a Member's Death?
The steps depend on the operating agreement, the member's estate plan, and state law. The process generally looks like this:
1. Review the operating agreement and estate plan. Start by checking what the operating agreement says about a member's death. It may name a successor, require the remaining members to buy the deceased member's interest, or limit who can become a member. You should also review the deceased member's estate plan, including any will or trust.
2. Find out who has legal authority to act for the estate. If probate is required, the court appoints a personal representative. This person manages the deceased person's estate and is responsible for collecting assets, paying debts and expenses, and distributing the remaining property to heirs or beneficiaries.
If there is a will, it may name an executor. If there is no will, or the person named cannot serve, state law determines who has priority to act as the personal representative. The rules and procedures vary by state.
3. List the membership interest as an estate asset. The personal representative includes the deceased member's LLC interest as part of the estate. A business valuation may be needed to determine its fair market value. This can be important for buyouts, taxes, and the distribution of assets among the beneficiaries or heirs.
4. Decide how the interest transfers. The next step is to determine what happens to the deceased member's ownership interest. Depending on the operating agreement and state law, heirs may receive the full membership interest, receive only the financial benefits of the interest, or the remaining owners may buy out the interest.
5. Update the LLC's records. Once the transfer is final, the LLC updates its member list, capital accounts, and operating agreement. Many LLCs record this through a written amendment signed by the members.
6. File any state updates and notify your bank and licensing offices. Some states list members or managers on public filings. If your state requires it, file an update with the Secretary of State. Then update your bank and any business licenses.
7. Handle tax and IRS updates.
- Notify the partnership of the death. If an executor receives the deceased partner's Schedule K-1 and the partnership interest is part of the estate, the executor should notify the partnership of the estate's name and taxpayer identification number. If another person receives the interest because of the partner's death, that person should provide the partnership with their name and taxpayer identification number.
- Know how the estate is treated for tax purposes. If your LLC is taxed as a partnership, the person who inherits the interest is generally treated as a partner for income tax purposes until the interest is bought out or otherwise ends.
What Happens to the EIN and Bank Accounts After LLC Member Death?
The LLC's EIN usually stays the same when an owner dies, as long as the business continues. What can change is the "responsible party" the IRS has on file, especially in a single-member LLC where the new owner or manager is a different person. That update goes through Form 8822-B, filed directly with the IRS at no cost. The IRS requires responsible party changes to be reported within 60 days.
Banks are usually stricter than the IRS about this. Many banks will freeze an account tied to a deceased sole signer until they see documentation, like Letters Testamentary or a court order, showing who's now authorized to act. If your LLC is ultimately closing rather than continuing, our guide to dissolving a business covers the dissolution steps.
How Can You Protect Your LLC Before an Owner Dies?
Delays are more likely when the LLC does not have a clear succession plan or the necessary documents in place. A few steps now can keep your business running smoothly later.
Write a death clause into your operating agreement. Spell out exactly who takes over management, how ownership transfers, and what timeline applies. This is one of the most effective ways to prevent your membership interest from being distributed as per the state's default rules.
Consider a living trust for your LLC interest. Placing your membership interest in a revocable living trust lets ownership pass to your chosen successor without waiting on probate court. Check your operating agreement first, since it may restrict transfers to a trust.
Draft a buy-sell agreement if you have partners. Set the valuation method and buyout terms in advance, ideally funded by life insurance, so surviving members aren't scrambling to come up with cash or negotiate a price during an already difficult time.
If your LLC's operating agreement doesn't address any of this yet, updating your operating agreement is the natural place to start.
Final Thoughts
An LLC doesn't have to fall apart when an owner passes away, but without a plan, the default rules and probate timelines can freeze it for months. A clear operating agreement and a buy-sell agreement, if you have partners, put your business and your family in a much stronger position. Swyft Filings has helped 600,000+ businesses since 2015 get their businesses set up the right way. If your LLC operating agreement doesn't have a succession clause yet, now's the time to put one in place.
FAQs
For a single-member LLC, the deceased owner's membership interest generally becomes part of the estate unless it was structured to pass outside probate. The operating agreement, estate plan, and state law determine who can receive the interest and become a member or manager.
Yes. Your children may be able to inherit your membership interest, either through your will, a living trust, or your state's intestacy laws if you don't have a will. Whether they can actively manage the business, versus just receiving profits, depends on your operating agreement and your state's law.
Placing your LLC membership interest in a properly funded revocable living trust can allow the interest to pass outside probate. Some states also allow a transfer-on-death designation for LLC interests, so it's worth checking what your state permits.
Not automatically, but it can happen by default if the operating agreement is silent and no one formally elects to continue the business within your state's window. This is why a death clause in the operating agreement matters so much for solo owners.