Key Takeaways
- An LLC for real estate investors can help separate personal and business liabilities.
- LLCs for real estate investment offer flexible ownership and management options.
- Tax treatment depends on the LLC real estate structure and investment type.
- Real estate LLC formation and ongoing compliance costs can add up.
- Choose an LLC structure that fits your real estate strategy.
Explore the key risks, benefits, and setup considerations before forming an LLC for real estate. Make informed decisions and choose the right structure from day one.
Real estate investing can take many forms, from long-term and short-term rentals to fix-and-flips, wholesaling, commercial properties, multifamily buildings, raw land, and passive investments in syndications. While an LLC is a common choice for many real estate investors, its benefits, tax treatment, and potential risks can vary depending on how you invest and how the LLC is structured.
Read this guide to know what an LLC can offer real estate investors, the risks and limitations to consider, and the key steps involved in setting one up for your investment strategy.
Benefits of an LLC for Real Estate Investors
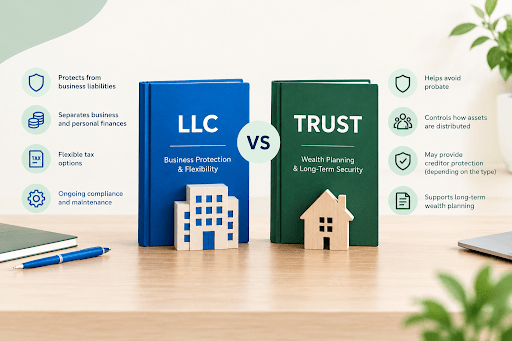
Depending on how the LLC is structured and operated, it may offer benefits related to liability separation, financial organization, taxation, ownership, and privacy. Here are some of the potential benefits to consider:
1. Liability Separation and Asset Protection
One of the main reasons real estate investors use LLCs is to separate the business's liabilities from the owner's personal assets. When an LLC owns an investment property, it generally becomes responsible for the property's obligations and liabilities.
For example, if a tenant makes a claim related to an LLC-owned rental property, the LLC may provide a layer of separation between the claim and the owner's personal assets.
2. Keeps Investment Activities Separate
An LLC can give investors a formal structure for separating real estate activities from their personal finances. This separation can make it easier to track rental income, maintenance costs, property taxes, insurance, and other expenses associated with an investment.
Some investors also use separate LLCs for different properties or investment activities. For example:
LLC 1 → Rental Property A
LLC 2 → Rental Property B
LLC 3 → Commercial Property
Separating properties into distinct entities may help keep the liabilities and finances of one investment separate from those of another.
3. Provides Flexible Ownership and Management
An LLC can accommodate different ownership arrangements, which can be useful when investing with business partners, family members, or other investors. An operating agreement can establish important details such as:
- Each member's ownership percentage
- Contributions from each member
- Distribution arrangements
- Voting rights
- Management responsibilities
- Rules for transferring membership interests
- Procedures for resolving disputes
This flexibility can make an LLC useful for both individual investors and real estate ventures involving multiple owners.
4. Offers Tax Classification Flexibility and Pass-Through Taxation
An LLC generally provides flexibility in how it is taxed for federal income tax purposes. Depending on factors such as the number of owners and tax elections, an LLC may be treated as a disregarded entity, partnership, or corporation for federal tax purposes.
Many LLCs receive pass-through tax treatment, meaning the business's income and losses generally pass through to its owners and are reported on their individual tax returns rather than the LLC paying federal income tax as a separate entity.
5. May Allow Deductions for Eligible Real Estate Expenses
Real estate investors may be able to deduct certain qualifying expenses associated with operating an investment property. Depending on the circumstances, these may include expenses such as repairs, maintenance, property management, insurance, and other property-related costs.
Depreciation may also be available for qualifying investment property. However, these potential deductions are not simply a result of forming an LLC. The tax treatment of an expense depends on applicable tax rules and the nature and use of the property.
6. Easier to Organize a Growing Real Estate Portfolio
As a portfolio grows, managing several properties personally can become more difficult. An LLC can provide a formal structure for organizing property ownership, income, expenses, contracts, and other investment activities. Some investors use one LLC for multiple properties, while others establish separate LLCs for individual properties or groups of properties.
For example, an investor with several rental properties might use an LLC structure to clearly track which property generates particular income and expenses. Separating properties into different LLCs may also provide greater separation between investments, though it entails additional costs and administrative requirements.
Risks of an LLC for Real Estate Investors
An LLC can provide useful liability and organizational benefits, but it does not eliminate the risks that come with owning real estate. So, before forming an LLC for real estate investing, consider the following potential risks and limitations.
1. Financing Challenges
Commercial lenders treat LLC-held property differently than owner-occupied lending. Expect:
- Higher down payments, often 20–30% instead of the 3–20% available on a conventional personal mortgage.
- Higher interest rates, since lenders view business-purpose loans as higher risk than owner-occupied loans.
- Personal guarantees. Many lenders will still require you to personally guarantee the loan, which partially defeats the liability separation you formed the LLC to get; if the LLC defaults, the lender can come after you personally anyway.
- Fewer loan options. Conventional 30-year fixed mortgages backed by Fannie Mae or Freddie Mac generally aren't available to LLCs; you are often limited to commercial or portfolio lenders.
This is consistently cited as the single biggest practical downside of holding real estate in an LLC.
2. The Due-on-Sale Clause
Real estate investors who already own a mortgaged property personally should consider the loan's due-on-sale clause before transferring the property to an LLC. A due-on-sale clause generally gives the lender the right to require repayment of the remaining loan balance when the property is transferred without the lender's consent.
Federal law provides exceptions for certain types of transfers. For example, the Garn-St. Germain Depository Institutions Act protects certain transfers into an inter vivos trust when the borrower remains a beneficiary, and the transfer does not involve a change in occupancy rights. The statute does not provide a general exemption for transferring a mortgaged property to an LLC.
3. Ongoing Costs and Compliance Burden
An LLC isn't a one-time cost:
- State filing fees at formation, typically 50–500.
- Annual or biennial report fees, required in most states to stay in good standing.
- Franchise taxes in some states regardless of income. California is the most cited example: an $800 annual minimum franchise tax under California Revenue and Taxation Code §17941, administered by the California Franchise Tax Board, owed even if the LLC made no money that year.
- Registered agent fees, an ongoing annual cost in every state.
- Publication requirements in a few states (New York, for example), which can add a real first-year cost.
For an investor with one low-value property, these recurring costs can outweigh the liability benefit, which is why "is it worth it for one rental" is a genuinely open question, not a rhetorical one.
4. Piercing the Corporate Veil
This is the risk that undoes everything else. Liability protection isn't automatic; a court can disregard the LLC entirely and hold you personally liable if you don't maintain it as a genuinely separate entity. Common triggers:
- Paying personal expenses from the LLC's bank account, or vice versa
- Not keeping a dedicated business bank account at all
- Undercapitalizing the LLC relative to the risk it's taking on
- Ignoring the operating agreement's own procedures (no member votes, no documentation of major decisions)
- Signing contracts personally instead of in the LLC's name
If a court pierces the veil, the entire point of forming the LLC is lost, and you're exposed exactly as if you'd never formed it.
5. Harder and Slower Ownership Transfers
Unlike a corporation, where selling stock is straightforward, transferring LLC ownership generally requires the consent of other members and formal amendment of the operating agreement. This matters for:
- Bringing in a new investment partner
- Exiting a deal
- Passing a property to heirs mid-portfolio
It's not necessarily a dealbreaker, but it's slower and more paperwork-heavy than investors sometimes expect going in.
6. Less Legal Precedent Than Older Entity Types
LLCs are newer than corporations and partnerships, so there's comparatively less case law addressing edge cases like how courts treat a series LLC in a multi-state dispute, for example, or exactly where the veil-piercing line falls in a given state. This isn't usually a dealbreaker for a typical rental or flip, but it adds some uncertainty in unusual disputes compared to more established structures.
7. Tax Classification Mismatches by Strategy
An LLC does not automatically determine how the IRS will tax your real estate income. The tax treatment can depend on what you do with the property and how the investment is structured.
For example, income from a long-term rental property is generally reported differently from profits earned through a fix-and-flip business. Investors who assume flip profits get rental-style passive tax treatment (or vice versa) can end up with an unexpected tax bill. The LLC changes who's liable, but it doesn't change how the IRS classifies the underlying income.
8. Privacy Isn't Guaranteed Everywhere
Some states allow you to keep member names off public LLC filings; many don't. If privacy from public property records is a specific goal, confirm your state's disclosure rules before assuming the LLC provides it; these vary enough that it shouldn't be treated as a default benefit.
Setup Considerations of an LLC for Real Estate Investors
Once you decide to use an LLC for real estate investing, there are several setup details to work through.
1. Match the LLC Structure to Your Strategy
The right structure depends on how many properties or deals you are running, not just that you are "investing in real estate":
- 1–2 properties or a single flip project: One LLC is usually enough.
- 3–10 properties, or multiple flips running at once: Consider a separate LLC per property/project, or a series LLC where your state allows it. This isolates a lawsuit or default on one deal from affecting the others.
- Larger portfolios or high flip volume: A holding company structure, where a parent LLC owns several operating LLCs, adds another layer of separation and can simplify financing and accounting across the portfolio.
- Passive investment in someone else's syndication: You typically don't form your own LLC at all. You hold a membership interest in the sponsor's entity instead.
Decide this before you file, since restructuring later (moving an already-titled property into a new LLC) means a second deed transfer, recording fees, and a fresh look at the due-on-sale question.
2. Choose the Right State to Register In
- Form where the property is physically located, in most cases. Forming in Wyoming, Delaware, or Nevada for their reputations, when your actual property sits elsewhere, typically just adds a second filing, meaning you still need to foreign qualify in the state where the property is, which means paying for and maintaining two states' worth of fees and registered agents.
- Multi-state portfolios need this evaluated on a property-by-property basis. An LLC holding rentals in three states generally needs to be foreign-qualified in the two states where it isn't originally formed.
- Compare formation and ongoing costs by state before deciding; filing fees generally run $50- $ 500, but ongoing costs (annual reports, franchise taxes) vary far more. California's $800 annual minimum franchise tax, administered by the California Franchise Tax Board, is the most-cited example of a state where ongoing costs matter as much as the initial filing fee.
3. Decide How to Handle an Existing Mortgaged Property
If you are transferring a property you already own and finance, rather than buying fresh into the LLC:
- Review your loan documents first for a due-on-sale clause, before filing anything.
- Consider a land trust as an intermediate step. Moving the property into a land trust first, then having the LLC hold the beneficial interest in that trust, is a strategy some investors use because land trusts are generally protected from acceleration under the Garn-St. Germain Act (12 U.S.C. §1701j-3). This needs to be set up correctly with an attorney; done informally, it can still trigger the clause.
- Talk to your lender directly in some cases. Some lenders will consent to the transfer, especially for a stable, performing loan, rather than risk losing a good borrower.
- New purchases don't have this problem. If you are buying fresh into the LLC with a new commercial or portfolio loan, the due-on-sale issue doesn't apply.
4. Need to Draft an Operating Agreement
Even a single-member LLC should have one; most states don't require it, but courts and lenders both look for it as evidence the LLC is a genuine, separate entity (relevant to avoiding a piercing-the-veil claim). What it should cover depends on your strategy:
- Holding/rental LLC: ownership percentages, profit and loss allocation, who has authority to approve repairs, sign leases, or sell the property, and an exit process if a member wants out.
- Flip-focused LLC: how capital and profit splits work per project, timelines, and who has decision authority on a purchase or sale.
- Multi-investor or syndication LLC: distribution waterfalls, voting thresholds, and capital call procedures.
Swyft offers a free operating agreement template as a starting point, as well as an operating agreement service if you don’t want to handle this by yourself.
5. Need to Open a Dedicated Business Bank Account
Every dollar of rental income, flip proceeds, or capital contributions should move through the LLC's own account, and every expense tied to that property or deal should be paid from it. Mixing personal and business funds is the most common way investors accidentally pierce their own liability shield. So, after formation of an LLC, you need to open a bank account.
6. Plan for Financing Before You Form, Not After
Since LLC-held property often means a larger down payment, a higher rate, and sometimes a personal guarantee, line up your financing approach before you file:
- Talk to a commercial or portfolio lender about what they will require for LLC-titled property.
- If you are planning to use a conventional mortgage and transfer into the LLC later, understand that's the path that raises the due-on-sale question above and decide going in whether you're buying into the LLC directly or transferring afterward.
7. Understand Your State's Privacy and Publication Rules
- Some states allow you to keep members' names off public LLC filings and others require them. If privacy is a specific goal, confirm this before you assume the LLC provides it.
- A few states, including New York, require newly formed LLCs to publish formation notices in local newspapers. So, an extra first-year cost worth budgeting for if you are forming there.
8. Set Up Bookkeeping That Matches Your Tax Classification
Because rental income, flip income, and land held for appreciation are taxed differently (passive vs. active, depreciable vs. not), set up separate bookkeeping categories from day one rather than lumping everything into one general ledger. This makes it far easier for your CPA to apply the correct treatment. Schedule E for rentals, active business treatment for flips without reconstructing the year at tax time.
Conclusion
Whether you are holding a long-term rental, flipping a house, running a short-term rental, or building a commercial portfolio, an LLC serves the same core function. It creates a legal wall between the property or deal and your personal finances.
That wall only holds up if the LLC is set up correctly and run as a genuinely separate business, meaning it has its own bank account, its own records, and no shortcuts. So, match the structure to your strategy, get the tax classification right with a CPA, and keep the LLC in good standing once it's formed. Ready to form your real estate LLC? Start your LLC with Swyft Filings and stay compliant from day one.
FAQs
An LLC can be useful for real estate investing because it may provide liability separation, flexible ownership, and a formal structure for managing property-related income and expenses. Whether it makes sense depends on the investor's properties, financing, state requirements, tax situation, and investment strategy.
Potential benefits include liability separation, easier financial organization, flexible ownership and management, and flexibility in federal tax classification. An LLC can also provide a structured way to manage one or more investment properties.
Not automatically. An LLC itself does not guarantee lower taxes. Federal tax treatment depends on the LLC's tax classification and the nature of the real estate activity. Rental properties, fix-and-flip activities, and other investments may be subject to different tax rules.
Requirements vary by state, and some states do not require an LLC to have a written operating agreement. However, an operating agreement can document how the real estate LLC will be owned and managed. It may address ownership percentages, capital contributions, profit distributions, management authority, property sales, member transfers, voting requirements, and dispute procedures. For multiple-property or multi-member investments, the agreement should reflect the actual investment structure and responsibilities.
LLCs and S corporations serve different purposes. An LLC can generally provide flexible ownership and management while allowing different federal tax classifications. An S corporation is a federal tax election with specific eligibility and ownership requirements rather than a separate state-law entity type. For many real estate investors, especially those primarily holding rental property, the LLC structure may offer a more straightforward ownership framework. The appropriate choice depends on the investment strategy and tax circumstances.
Common mistakes include choosing a structure without considering the investment strategy, failing to review financing requirements, transferring a mortgaged property without checking the loan documents, mixing personal and LLC finances, failing to maintain required records, overlooking state compliance deadlines, and assuming an LLC automatically provides complete asset protection. Investors can also run into problems when the operating agreement does not accurately reflect ownership or management arrangements.
The cost varies significantly by state. Investors may have to pay an initial formation fee as well as recurring annual or biennial report fees, franchise taxes, registered agent fees, and other state-specific costs. Some states also have additional requirements, such as publication expenses. Because fees and requirements can change, investors should check the current costs in the state where the LLC will be formed and any states where it may need to register as a foreign LLC.